Travel Value Finder
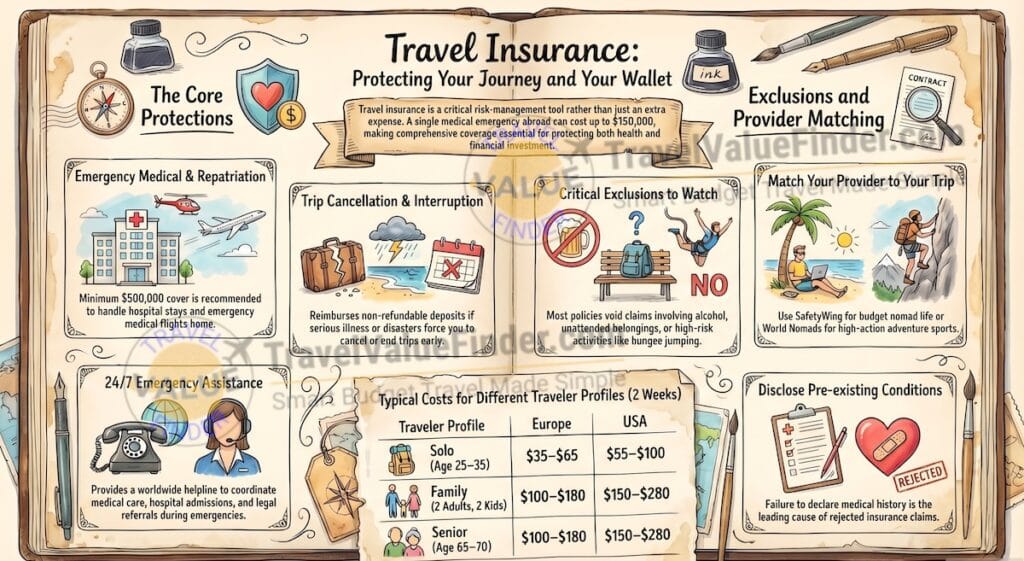
Knowing how to choose travel insurance starts with matching coverage to your actual trip risks. This guide compares coverage types, real 2026 prices, and the mistakes that get claims denied. Use it to pick a policy built for your trip, not a generic default.
A single hospital stay abroad can run past $50,000, and that excludes the flight home. Most travelers never file a claim. The ones who do usually call it the cheapest part of the trip.
By Leslie Nics, TravelValueFinder.com. Last updated September 2026.
This article is for general information only. It is not financial, medical, or legal advice. Costs and terms change, so confirm current details with your insurer.
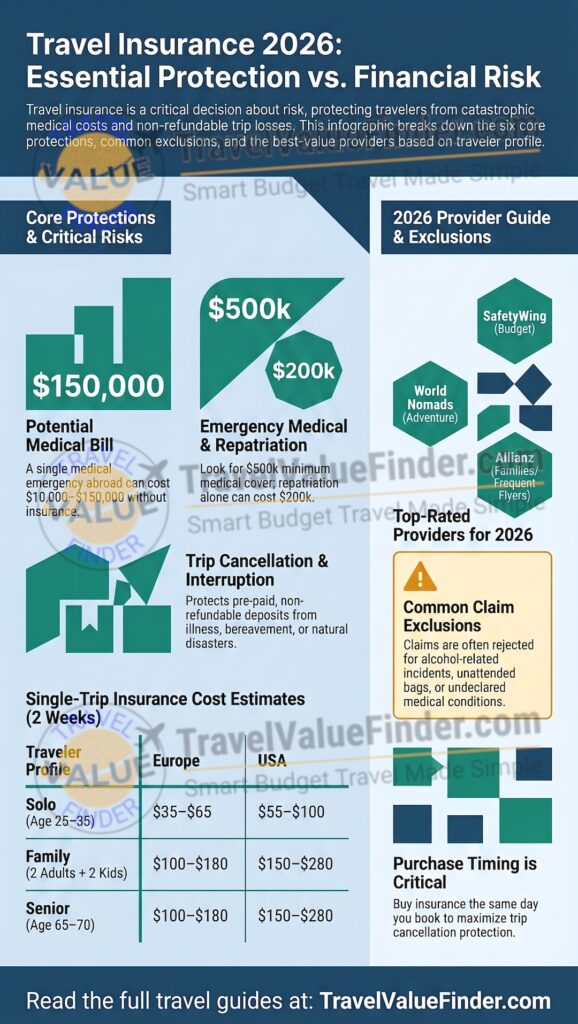
Table of Contents
Quick Answers About Travel Insurance
Here are fast answers to the questions travelers ask most.
Do I need travel insurance for a domestic trip?
Yes, if you have nonrefundable bookings. Medical cover matters less since your home insurance usually applies.
How much coverage should I buy?
Aim for at least $100,000 in medical cover. Pick $250,000 or more for the United States, Canada, or Australia.
Can I buy insurance after I book my trip?
Yes, but buy it early. Cancellation cover only protects events that happen after your purchase date.
Does travel insurance cover a canceled flight?
Yes, for covered reasons like illness or severe weather. It will not cover a simple schedule you dislike.
What a Travel Insurance Policy Should Cover
Every solid policy covers six core risks. Skipping any one of these leaves a real gap. Compare the table below against any plan you are considering.
A policy that only handles cancellation looks cheap but leaves your health exposed. A policy that only handles medical care leaves your deposits unprotected. You want both working together.
| Coverage Type | What It Pays For | Typical Limit |
| Emergency medical | Hospital care, surgery, and doctor visits abroad | $100,000 to $500,000 |
| Medical evacuation | Flying you home for urgent treatment | $250,000 to $1,000,000 |
| Trip cancellation | Prepaid costs if you cannot travel | Full trip cost |
| Trip interruption | Costs if you cut a trip short | Full trip cost |
| Baggage loss | Stolen, lost, or damaged luggage | $1,000 to $2,500 |
| Travel delay | Meals and hotels during a long delay | $100 to $300 per day |
| Personal liability | Injury or damage you cause to others | $25,000 to $100,000 |
Medical evacuation is the line item people underestimate most. A long flight home with a medical team can outcost the rest of your trip. Check this limit first, before you look at price.
Pair full coverage with smart packing so nothing valuable sits exposed. Our packing list guide helps you travel light and keep track of your gear.
Domestic Trips and International Trips: Different Needs
Domestic travel insurance leans on cancellation and baggage cover. Your regular health insurance usually still applies at home. The math changes completely once you leave the country.
International travel insurance leans hardest on medical and evacuation limits. Your home health plan often stops working the moment you cross a border. This gap is where most costly surprises happen.
| Trip Type | Main Risk | What Matters Most |
| Domestic | Lost prepaid bookings | Trip cancellation and interruption limits |
| International | Medical bills abroad | Emergency medical and evacuation limits |
How to Choose Travel Insurance for Your Type of Trip
Your trip type shapes what actually matters in a policy. A ski trip and a beach vacation carry very different risks. Match your coverage to the trip you are actually taking.
| Trip Type | What to Prioritize |
| International trip with prepaid bookings | High cancellation limit and full medical cover |
| Adventure trip like skiing or diving | Adventure sports add on and a high evacuation limit |
| Cruise | Cabin confinement cover and missed port protection |
| Schengen visa trip | Minimum thirty thousand euro medical cover valid zone wide |
| Family trip with children | Family rate plans and pediatric medical cover |
| Trip with an existing health condition | Specialist insurer with disclosed condition cover |
A cruise and a ski trip look nothing alike on paper. One needs strong cabin and port cover. The other needs a sports rider and a high medical limit for mountain rescue.
Heading to Europe on a Schengen visa? Our guide to traveling Europe on a budget covers visa costs alongside your trip planning.
What Affects Your Premium
Insurers price a policy using a handful of factors. Knowing these helps you understand your quote. It also shows you where you can trim cost without cutting real protection.
| Factor | How It Affects Price |
| Age | Premiums rise steadily after 50 and again after 65 |
| Trip cost | Cancellation cover scales with your total prepaid spend |
| Trip length | Longer trips raise both medical and cancellation premiums |
| Destination | The United States and Canada carry the highest medical rates |
| Add ons | Adventure sports and cancel for any reason both raise price |
Cutting your medical limit to save money is rarely worth it. A low medical cap can cost far more once you actually need care.
Why Insurance Claims Get Rejected
Most denied claims trace back to a few avoidable causes. Reading your policy wording before you travel prevents most of them. The table below covers the most common reasons.
Insurers are not trying to trap you. They pay claims that match the wording you agreed to at purchase.
| Reason | What It Means |
| Undisclosed health condition | Insurers void claims tied to conditions you did not report |
| Unattended belongings | Leaving a bag alone in public voids most theft claims |
| Known events before purchase | A storm or strike announced before you bought is excluded |
| Risky activity without add on | Skiing or diving needs a separate rider on most plans |
| Travel against medical advice | Claims are void if a doctor advised against the trip |
| Simple change of mind | Standard plans exclude cancellation for personal preference alone |
Read the exclusions page before you buy, not after something happens. It takes five minutes and shows exactly what a cheap policy skips.
What Travel Insurance Costs in 2026
Price depends on your age, trip length, and destination. Older travelers and longer trips cost more. Use this table as a starting point, not a quote.
| Traveler Profile | Typical Cost Per Trip | Typical Annual Cost |
| Solo traveler, 25 to 40 | $30 to $90 | $150 to $250 |
| Solo traveler, 55 to 70 | $80 to $220 | $300 to $600 |
| Couple, under 50 | $60 to $150 | $250 to $450 |
| Family of four | $90 to $200 | $350 to $600 |
These ranges assume a standard medical plan without extra riders. Adding adventure sports or cancel for any reason cover raises the price. Always request the exact quote for your own dates.
Add this cost into your trip math with our travel budget calculator.
Group and Student Travel Insurance
Group trips and study abroad programs need slightly different cover. Group policies often bundle several travelers under one plan. Student plans usually run longer and include routine care, not just emergencies.
| Traveler Type | Key Difference |
| Group trip | One policy covers everyone, often at a lower per person rate |
| Study abroad | Longer terms with routine and mental health care included |
| Volunteer or work trip | May need liability cover for the host organization |
Check your program’s insurance requirement before you shop. Many schools and volunteer organizations set a minimum coverage level you must meet.
Single Trip or Annual Plan: A Three Question Test
Ask yourself three quick questions before deciding. Your answers point straight to the better option. This beats guessing based on price alone.
- Will you take more than two trips this year?
- Are your trips usually shorter than sixty days?
- Do you want continuous cover without buying a new plan each time?
Answering yes to all three points to an annual plan. Answering no to most points to a single trip policy.
| Factor | Single Trip | Annual Plan |
| Best for | One or two trips a year | Three or more trips a year |
| Typical cost | $30 to $150 per trip | $150 to $400 per year |
| Trip length limit | None | Usually 31 to 90 days per trip |
Annual plans break even for most travelers around the third trip. Track your own travel pattern for a year before committing. Past habits usually predict the better fit.
How Insurance Providers Compare
No single provider fits every traveler. Compare a few based on how you actually travel. This snapshot covers common traveler types.
| Provider | Best For | Starting Price |
| SafetyWing | Long term and budget travelers | $45 per month |
| World Nomads | Adventure sports and activities | $70 per trip |
| Hey Mondo | Flexible cover across age groups | $30 per trip |
| Allianz Global | Families and frequent travelers | $100 per year |
| AXA Assistance | Comprehensive cover with high limits | $50 per trip |
| Battleface | High risk or remote destinations | $40 per trip |
TravelValueFinder earns no commission on insurance providers. This comparison is independent and based on published coverage details.
Prices change often, so treat these figures as a starting point. Always pull a live quote for your exact trip before deciding.
Special Cases: Visas, Older Travelers, and Existing Conditions
A few traveler groups face extra rules beyond the standard policy. These cases are worth checking closely before you buy. Getting them wrong can mean a denied visa or a denied claim.
Many non EU travelers need proof of insurance for a Schengen visa. The minimum required medical cover is thirty thousand euros. The policy must be valid across every Schengen country and include repatriation.
UK travelers can use the Global Health Insurance Card for state healthcare in the EU. It does not cover repatriation, cancellation, or private treatment. Carry it alongside a full policy, not instead of one.
Standard insurers often cap coverage around age 65 to 70. Specialist senior insurers extend cover into the eighties. Expect detailed health questions and answer them fully and honestly.
A preexisting condition is one you were treated for before buying the policy. Most insurers look back one to five years. Disclose everything, since a missed detail can void your entire claim.
Some insurers offer a medical screening waiver. It applies if you buy soon after booking, often within ten to twenty one days. Ask your insurer if this applies to you.
How to File a Claim When Something Goes Wrong
A smooth claim starts the moment something happens, not weeks later. Keep paperwork as you go. Insurers pay faster when the evidence is already organized.
- Call the insurer’s emergency line before you pay for major medical care.
- Get a police report for theft and a doctor’s note for illness.
- Keep every receipt, boarding pass, and cancellation notice you receive.
- File your claim online as soon as you are able to.
- Follow up in writing if you do not hear back in two weeks.
Most straightforward claims settle within two to four weeks. Complex medical claims can take longer, especially with hospitals in different countries. Patience and clear documentation move things along faster than complaints do.
Buying Checklist: How to Choose Travel Insurance Before You Pay
Run through this list before you enter your card details. It takes about fifteen minutes and prevents most of the regret people feel later.
- List your destination, trip length, age, and planned activities.
- Compare at least three policies side by side, not just price.
- Open the exclusions section and read it fully.
- Check any existing cover you already have through other policies.
- Buy the same day you book your trip if possible.
- Save your policy number and emergency line somewhere offline.
Common Mistakes That Cost Travelers Money
These mistakes show up again and again in denied claims. Most are easy to avoid once you know what to watch for.
- Buying the cheapest plan without checking coverage limits.
- Forgetting to declare a health condition to save a few dollars.
- Assuming an embassy will cover medical bills abroad.
- Waiting until the week before departure to buy cover.
- Leaving bags unattended at a cafe or beach.
- Skipping the fine print on adventure sport exclusions.
None of these mistakes are complicated to fix. A few extra minutes at checkout is usually all it takes.
Sources
The figures and requirements above draw on the following official and industry sources.
- U.S. Department of State, Bureau of Consular Affairs, travel insurance guidance
- Centers for Disease Control and Prevention, travel health guidance
- European Commission, Schengen visa insurance requirements
- National Association of Insurance Commissioners, travel insurance consumer guide
- UK National Health Service, Global Health Insurance Card information
Frequently Asked Questions
What is the difference between travel insurance and travel medical insurance?
Travel medical insurance only covers healthcare costs abroad. Full travel insurance adds cancellation, baggage, and delay cover too.
Will travel insurance cover a preexisting health condition?
Sometimes, if you disclose it and buy within the insurer’s window. Specialist insurers offer broader preexisting condition cover.
What does cancel for any reason coverage do?
It lets you cancel for reasons a standard policy excludes. It usually refunds about half to three quarters of your trip cost.
Does travel insurance cover natural disasters?
Yes, if the disaster was unknown when you bought the policy. Cover typically includes evacuation and trip interruption costs.
How soon before my trip should I buy insurance?
Buy the same day you book, ideally. This starts your cancellation cover as early as possible.
Is annual travel insurance worth it for frequent travelers?
Usually yes, past two or three trips a year. It also removes the hassle of buying a new plan every time.
Does travel insurance cover lost luggage?
Yes, up to a per item and total limit. File an airline report first, since insurers require that reference number.
Do I need travel insurance if I already have health insurance at home?
Usually yes, since most home health plans stop paying once you leave the country. Check your plan’s international clause before you assume you are covered.
This is My Take on Travel Insurance
The right policy fits your actual trip, not a generic template. Take twenty minutes to compare real coverage limits. Then get back to planning the parts of your trip you’re excited about.
A little research now saves a lot of stress later. The best policy is the one that matches your real risks. Everything else is just paperwork.
Keep a copy of your policy details on your phone and on paper. A backup matters most exactly when you least expect to need it.
Once your coverage is sorted, plan your days with our guide to free walking tours.